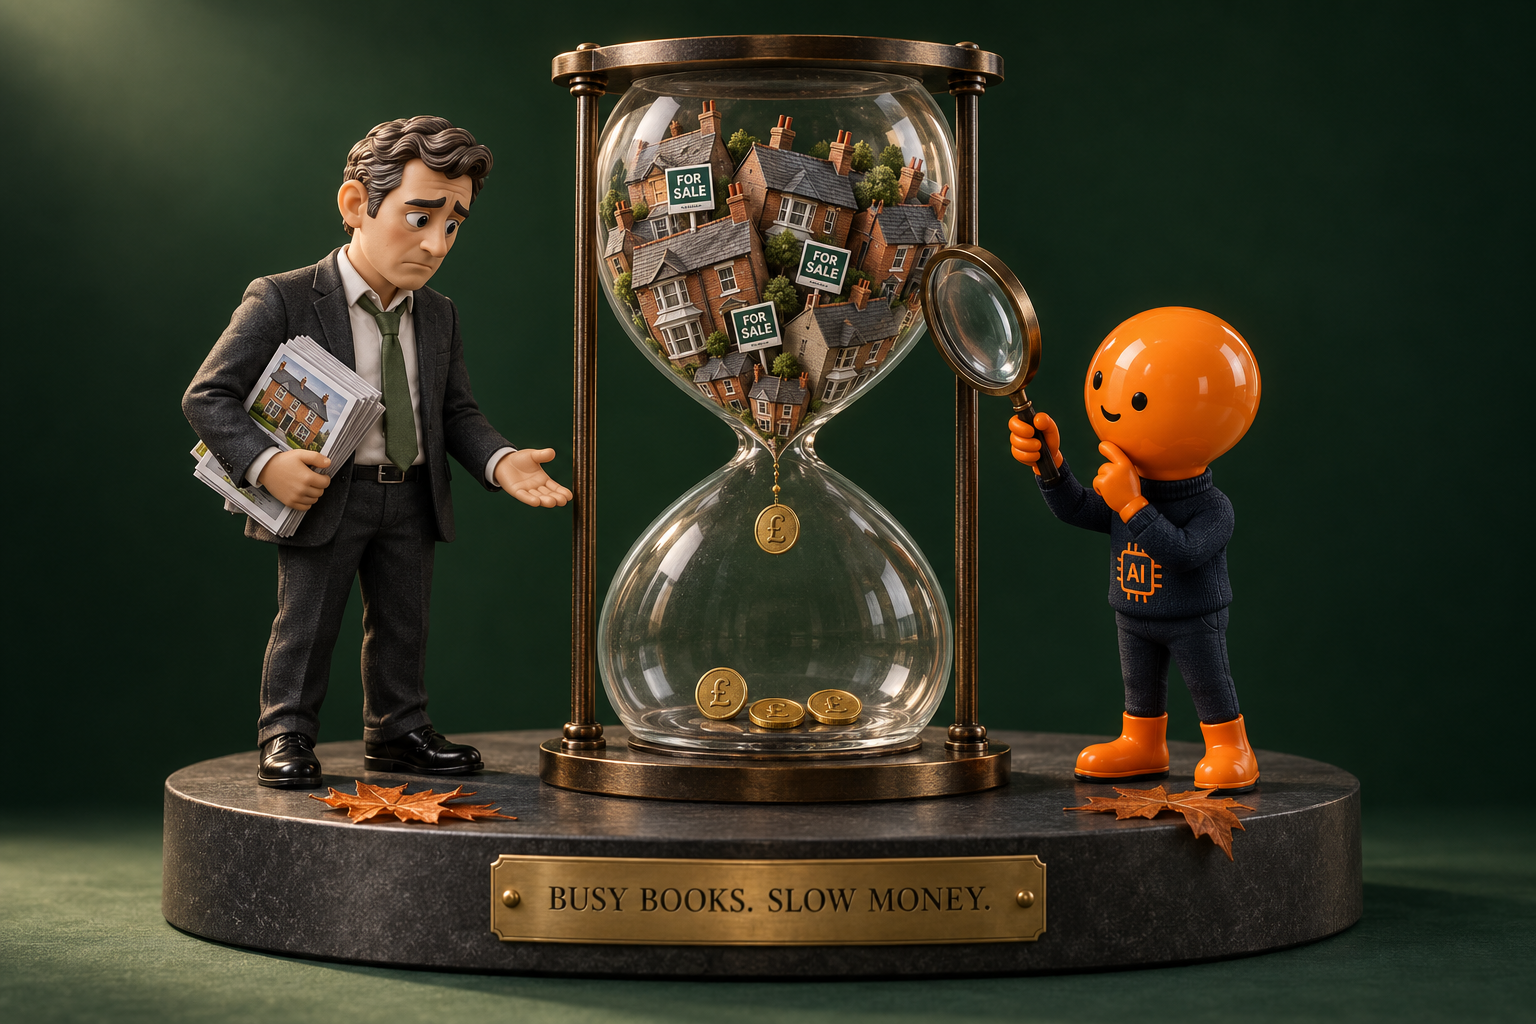
I’ve been speaking to agents about the autumn market and the mood is … careful. Not universally doom-laden, but certainly not buying the cheery “seasonal bounce” narrative at face value either.
A town full of your boards looks comforting from the outside, of course - what better way to very demonstrably show that you're better, more popular, more successful, more damn handsome/pretty than every single one your competitors. The intoxication of intimidation, skewering everyone else with your seller skillsets.
Inside the business, you know that 'stock' and saleable stock' are two very different beasts. One fills those windows and keeps the vendor-awareness drum beating. The other turns into fees within a timeframe your bank account can actually pay essential bills with.
The comfortable take on autumn is: supply is fine, demand is having a lie-down until mortgage rates behave themselves. Yet the numbers don’t just suggest “more choice”; they suggest a market that’s struggling to clear what it already has.
Rightmove’s September figures put available homes at a 12-year high for the time of year, even as new listings were down 3% year-on-year. At the same time, buyer enquiries and sales agreed were both down 9%. Fewer instructions arriving, fewer deals being agreed, and plenty still on the shelf. That doesn’t scream “healthy balance”; it screams 'incoming angry vendors'.
Then Zoopla adds another revealing layer: a quarter of homes newly listed in September had already been marketed within the previous year. 60% of those returned at a lower asking price; the rest came back at the same.
Do the maths and you’re looking at roughly one in ten “new listings” actually being relaunches at an unchanged number. That’s a chunky slice of the market potentially playing the insanity game - re-running the same experiment and hoping for a different result.
Now, relisting doesn’t automatically mean “bad instruction”. Chains collapse, circumstances change, refurbishments get finished, previous agents mishandle it. A relaunch tells you very little about quality on its own. But it tells you something hugely important: “new to market” is often a branding term, not a truth.
And that history is commercially useful. It contains evidence: enquiry levels, viewing friction, objections, offers (or the absence of them), price changes, and - crucially - how the seller reacted when reality started tapping them on the shoulder. Put a different board up and it’s remarkably easy for reporting (and sometimes internal dashboards) to pretend the story starts again. Buyers, however, can be irritatingly good at remembering the last chapter.
Rightmove says 61% of homes are finding a buyer, versus 74% in 2021. Finding a buyer still leaves you the long walk to completion, of course. And that national number hides massive local variation: 91% in Scotland and 42% in London, per Rightmove’s own index. Any strategy built around “the UK market” is already binning useful information.
For an agency, the question isn’t whether the index is up or down this month. It’s: how much of +our+ stock converts to revenue, how long it takes and how much staff time it eats on the way.
There’s also a structural tension in a no-sale-no-fee model that rarely gets said out loud. A vendor with no deadline can afford to “test the market” at last year’s number. The agent largely funds that test - marketing costs, portal spend, photography, viewings, negotiation time, opportunity cost. The seller’s patience has a cost. Some of it sits in somebody else’s P&L.
That’s why I’m less interested in yet another sermon about “overvaluation”, and more interested in whether businesses are pricing this risk properly into their expectations. Does your fee forecast distinguish a motivated seller with a review plan from a vendor who’ll only move if someone overpays? Does it treat a returning instruction with a resolved obstacle differently from one whose history is about to repeat itself? Or do they both enter the pipeline at the full, optimistic fee number?
This is where AI and proptech can do something genuinely useful - something beyond producing another confident valuation paragraph.
The prize is preserving the property’s marketing history, surfacing comparable outcomes properly, and estimating likelihood of sale and time-to-fee with transparent reasoning. What changed since last time? What didn’t? What’s the next action most likely to shift the outcome: a price conversation, resolving a lease query, qualifying the buyer position, nailing down onward plans?
Sometimes the negotiator will know the system has missed something instantly. Brilliant. That correction is data. That’s how you build something that actually reflects the real world, rather than a tidy model that’s an elegant way to be wrong.
If you want a practical starting point using data most agencies already hold: take instructions won in Q1 and track what actually happened. Split first-time listings from relaunches. Track withdrawals, time-on-market, reductions, fall-throughs, fees banked, and work still outstanding. Keep the unresolved cases visible rather than quietly treating them as either “basically sold” or “never mind”.
This sounds complicated - but it's not. Bung it into Claude or ChatGPT (make sure you're on a £20 paid plan and you've switched the "don't train on my data' toggle). Then ask the question: which early signals were genuinely predictive in time to change behaviour?
Because this autumn, the difference between “busy books” and “slow money” may be the difference between a decent quarter and a ruinously expensive one. And the returning stock will contain some of the best opportunities - if you can spot early which relaunch is a fresh start as opposed to the one that's just last year’s stalemate with a new board.